


Opening a bank account abroad does not always require permanent residency or a long-term residence visa. In Asia, selected banks in Hong Kong, Singapore, Cambodia and the United Arab Emirates offer routes for eligible foreign applicants.
However, the requirements differ. Some banks accept overseas customers, while others require evidence of a local connection, such as accommodation, employment or business ownership.
For investors, frequent travellers and families preparing to relocate, an overseas account can be useful. Its value may come from holding foreign currencies, managing expenses or accessing banking services across borders. Any tax benefit requires a separate assessment.
Why Would You Need a Bank Account Abroad?
Hold Money in Different Currencies
An overseas account can help you keep funds in the currency you expect to spend.
For example, a family preparing for overseas education may want to hold money for tuition and living expenses. An investor may need foreign currency for an upcoming investment.
This can reduce repeated conversions, although holding another currency introduces exchange-rate risk.
Make Payments When You Travel or Relocate
A suitable local account can make it easier to pay rent, bills and everyday expenses during an extended stay.
It may also help you prepare for a move before obtaining permanent residency, where the bank accepts nonresident applicants.
Manage International Transfers
An international account may help you organise transfers between countries. Before choosing one, compare transfer charges, intermediary-bank fees and exchange-rate margins.
An account with a low monthly fee can still be expensive if its currency conversion costs are high.
Diversify Where You Keep Savings
Keeping funds with more than one bank can provide an additional way to access money if your main account or payment card becomes temporarily unavailable.
The protection available depends on the jurisdiction, bank, currency and account type. A foreign account should be assessed on those terms, alongside convenience.
Earn Interest With Favourable Local Tax Treatment
Some jurisdictions exempt qualifying personal bank deposit interest from local tax. This can be relevant when comparing savings accounts.
However, local tax exemption does not necessarily mean the interest is tax-free for you overall. Your country of tax residence may still tax it.
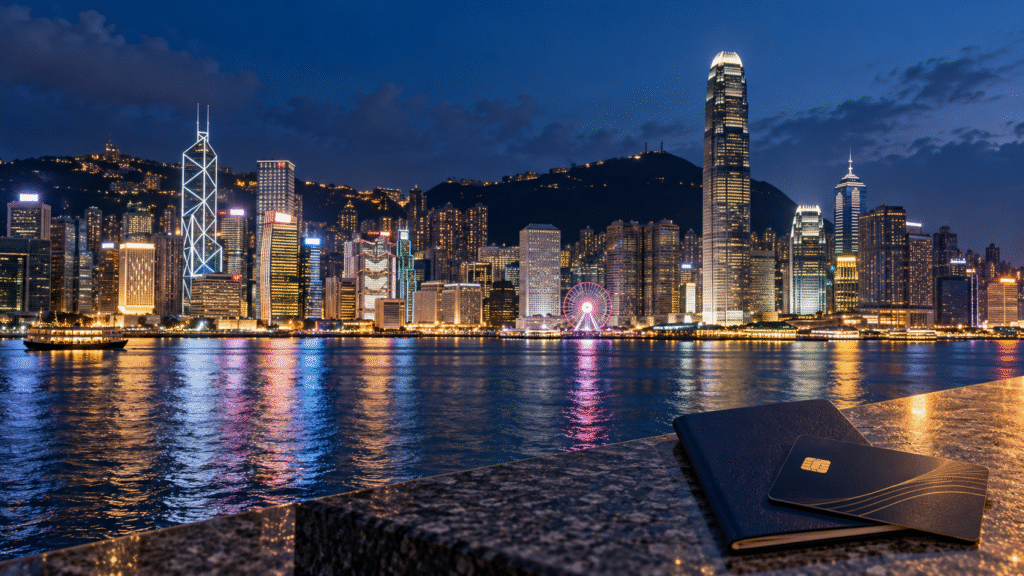
Selected Hong Kong banks accept eligible overseas applicants without permanent residency.
Hong Kong: Overseas Applicants Have Banking Options
Do you need permanent residency or a long-term visa?
Not necessarily. Eligible overseas applicants can apply through selected banking routes.
HSBC Hong Kong accepts eligible overseas passport holders. Its application methods depend on your passport, country of residence and location when applying. Applicants may need proof of identity, proof of address and additional documents. Branch applications are also available, subject to eligibility.
Why might you consider it?
A Hong Kong account may be useful if you regularly manage financial commitments in the jurisdiction or want banking access before a future move. Confirm which currencies, transfers and investment services are available to your particular customer profile.
What is the tax position?
Qualifying interest from deposits with Hong Kong financial institutions is generally exempt from Hong Kong profits tax. Exceptions include certain deposits used as security for borrowing where the borrowing interest is tax-deductible.
That treatment applies to qualifying deposit interest. It does not make all business income or investment returns received into the account tax-free.
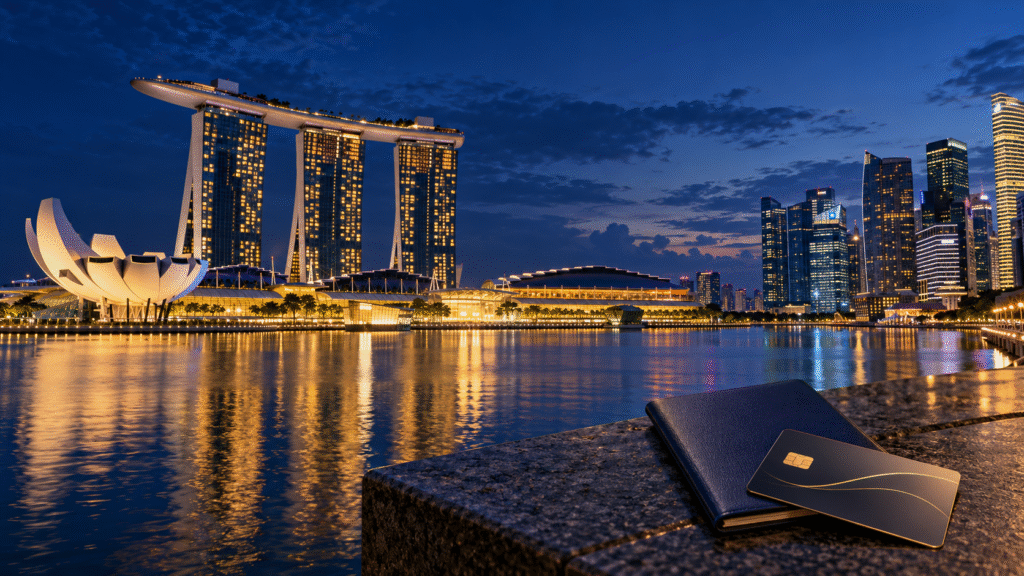
Selected international banking routes serve eligible applicants living outside Singapore.
Singapore: International Banking Routes for Eligible Applicants
Do you need permanent residency or a long-term visa?
Selected international application routes may be available without these, subject to the bank’s acceptance.
HSBC Singapore offers applications from overseas. However, some standard digital routes require proof of a Singapore residential address. Applicants living abroad should confirm the appropriate international route directly with the bank.
Why might you consider it?
A Singapore account may suit someone preparing for a move, supporting family expenses there or managing international finances through a bank that accepts their overseas residence.
Check the balance requirements carefully. The conditions for an ordinary account may differ from those for Premier or other relationship-based services.
What is the tax position?
For individuals, interest from deposits with approved banks in Singapore is not taxable in Singapore. Other interest sources and investment arrangements can receive different treatment.
This is a specific benefit for qualifying deposit interest, rather than a general exemption for money received into a Singapore account.
Foreign applicants may open selected Cambodian accounts with accepted entry documents and supporting evidence.
Cambodia: Possible Without PR, but Supporting Documents Matter
Do you need permanent residency or a long-term visa?
Permanent residency is not listed in ABA Bank’s published foreign-applicant requirements. A long-term visa is one way to meet its documentation requirements, but alternatives are listed.
ABA requires a valid passport and valid Cambodian visa or accepted entry stamp, plus specified evidence of residency status. Alternatives include qualifying accommodation documents, employment evidence or proof of business ownership. Several options require evidence covering at least six months.
A short-stay visa alone does not satisfy ABA’s full published checklist. Confirm your eligibility with the bank before travelling.
Why might you consider it?
For someone with ongoing commitments in Cambodia, an account can support local payments and transfers. ABA offers savings accounts in USD and Cambodian riel, with mobile banking access.
What is the tax position?
Cambodia should not be presented as a tax-free banking destination. CIMB Cambodia states that interest on its referenced savings product is subject to withholding tax of 4% for residents and 14% for nonresidents.
For illustration, USD 1,000 of gross interest subject to 14% withholding leaves USD 860 after Cambodian withholding, before fees and any tax payable elsewhere. Confirm how the bank classifies you for tax purposes.
Selected UAE savings accounts offer application routes for nonresidents, subject to bank approval.
UAE: Selected Savings Accounts for Nonresidents
The UAE provides a West Asian option for applicants considering banking beyond Southeast and East Asia.
Do you need permanent residency or a residence visa?
Selected nonresident savings accounts have a separate application route.
Emirates NBD’s Currency Passport Savings Account lists requirements for nonresidents, including a passport with visa page and supporting documentation such as a recent utility bill, bank statement or home-bank reference. Additional documents may be required.
Why might you consider it?
It may be relevant if you have financial commitments in the UAE and need an account before becoming a resident. Confirm the available currencies, minimum balance, transfer facilities and whether an in-person visit is required.
What is the tax position?
The UAE does not levy personal income tax. However, individuals conducting qualifying business activities may fall within corporate tax rules.
Receiving salary or client payments into a UAE account does not, by itself, remove tax owed in another country.
Which Option Fits Your Purpose?
Start with what you need the account to do:
- For qualifying savings interest: Singapore and Hong Kong offer favourable local treatment.
- For ongoing expenses in Cambodia: A Cambodian account may be useful if you meet the bank’s documentation requirements, but interest withholding matters.
- For financial commitments in the UAE: Selected nonresident savings accounts may provide access before residency.
- For a future relocation: Choose a bank that explicitly accepts your current overseas residence.
These are possible application routes, rather than guarantees of approval. The same bank may apply different requirements to different passports, residences and account types.
Banking Residency and Tax Residency Are Different
A bank accepting you as a nonresident customer does not determine your tax residency.
Tax residency follows the laws of the relevant jurisdictions. Banks may require you to disclose all countries where you are tax resident and provide applicable tax identification numbers. Reportable account information may be exchanged with tax authorities under the Common Reporting Standard.
To assess tax efficiency, look at the income earned, local withholding, tax payable elsewhere and account costs together.
What Should You Confirm Before Applying?
Ask the bank whether it accepts your nationality and current residence, which visa or entry documents it needs, and whether you must visit a branch.
Also confirm the minimum balance, maintenance fees, international transfer charges and access arrangements after you leave the country. If you intend to receive business payments, ask whether a separate business account is required.
An overseas account is most useful when it solves a clear financial need. Choose it around your payments, currencies and future plans, then assess the tax consequences of the income it earns.